• Home
  • Technology
  • Gaming
  • Entertainment
  • World & Business
  • Science
  • Sports
  • AI
HomeTechnologyGamingEntertainmentWorld & BusinessScienceSportsAI
World & Business
Report

Micron earnings beat puts memory prices and margin guidance in focus

An earnings-focused account says Micron’s revenue rose 79% year over year, with most of the growth coming from prices rather than bit volume. Another post claims a $150 billion contract backlog.

FI
MM
ER
9 Sources, 9h ago, first seen 9h ago

TLDR

CNBC describes Micron’s earnings as a beat. An earnings-focused account says higher prices drove most of a 79% year-over-year revenue increase and argues that the outlook depends on how long prices hold. Another post claims a $150 billion contract backlog and forecasts another record quarter. A separate post describes gross-margin guidance of 86% as declining and warns about a potential cyclical downturn in memory stocks.

Combined views

144.9K

9 Sources, first seen 9h ago

601 likes108 comments101 saves69 reposts
Featured Source

Combined views

144.9K

9 Sources, first seen 9h ago

601 likes108 comments101 saves69 reposts

Sentiment

Positive——Negative

Summary

Not enough discussion yet.

No sentiment analysis available yet.

Sentiment

Positive——Negative

Summary

Not enough discussion yet.

No sentiment analysis available yet.

9 Sources

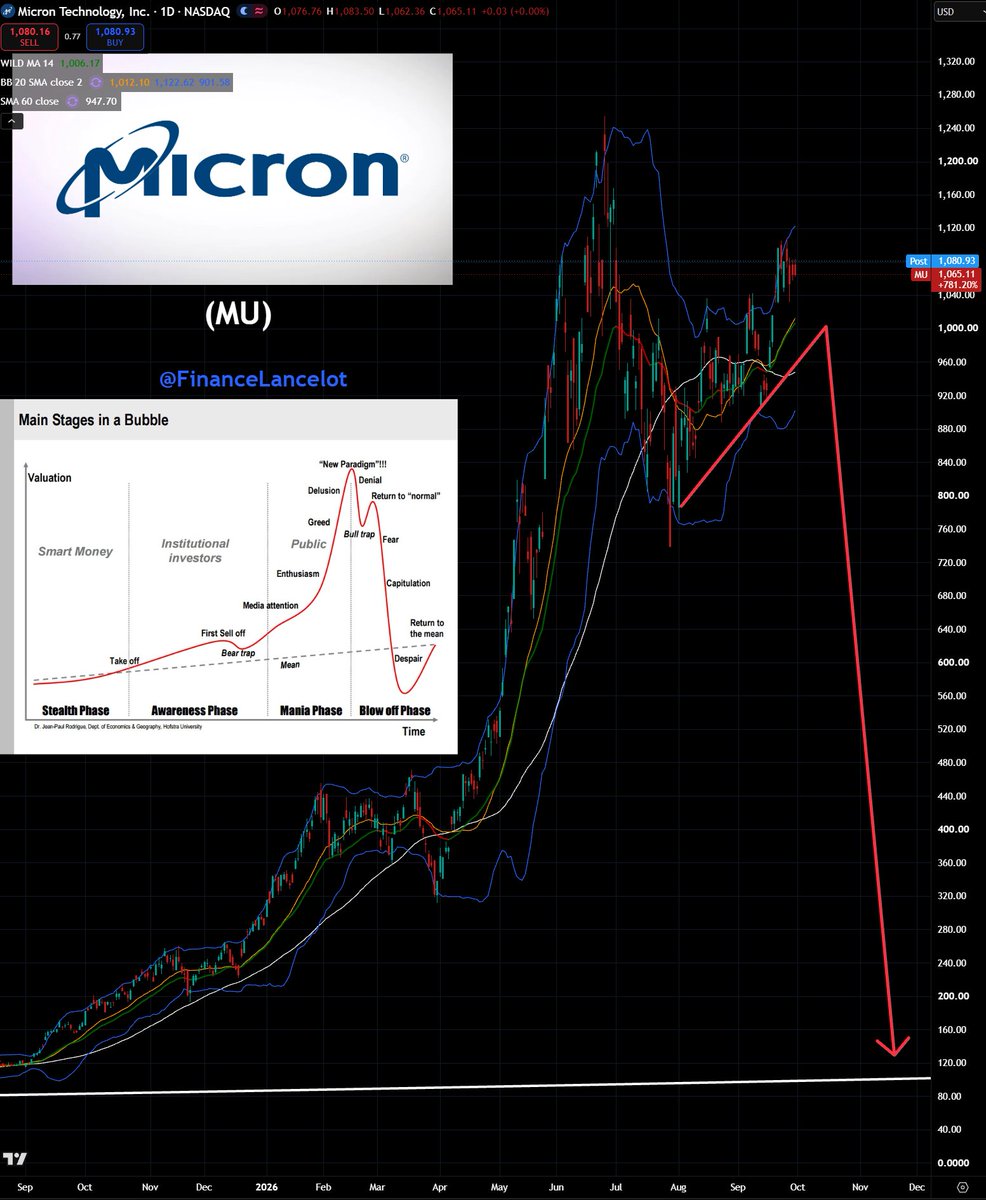
@FinanceLancelotBREAKING: Micron $MU beats earnings estimates but reports a declining gross margin guidance of 86% 🚨 Memory stocks have always begun their cyclical decline when gross margins peak.
@mwmarketwire🚨 MU’S BLOWOUT EARNINGS MAY ACTUALLY BE A WARNING FOR THE AI BOOM Everyone is celebrating Micron’s massive numbers. And yes ,for $MU, they are incredible. But I see something else. 🟦 MEMORY IS BECOMING MORE EXPENSIVE AI demand for HBM and memory remains enormous. Scarcity = pricing power. Great for Micron. But remember: Micron’s higher revenue is somebody else’s higher cost. And that somebody is increasingly the AI industry. 🟦 LOOK AT WHAT AI ALREADY REQUIRES GPUs. HBM / memory. Data centers. Electricity. Cooling. Networking. And increasingly: DEBT. Now add higher memory prices and expensive financing. The infrastructure bill keeps getting bigger. 🟦 BUT WHERE IS THE RETURN? This is the part almost nobody wants to discuss while AI stocks keep making new highs. OpenAI, Anthropic and xAI are growing revenues rapidly. But they are also burning enormous amounts of capital building and operating AI. And at the same time, competition is pushing the price of AI lower. DeepSeek. Chinese models. Open-source models. More competition every month. So think about this: The inputs are scarce and expensive. While… The output is becoming cheaper. 🟦 THIS IS THE AI PARADOX AI can become one of the most important technologies in history… and the investment boom behind it can STILL become financially unsustainable. Because technological success does not automatically equal: PROFIT. $MU gets paid. $NVDA gets paid. Data centers get paid. Energy companies get paid. Creditors get paid. But who ultimately captures enough profit to justify the TRILLIONS being invested into AI? That is the question I believe the market is massively underestimating. 🟦 MU’S NUMBERS DIDN’T MAKE ME MORE BULLISH ON THE AI BOOM. They made me question its economics even more. AI demand is real. The technology is real. The spending is real. But where is the return? #MWMarketWire
@_EarningsRadar$MU revenue is up 79% Y/Y — but bit volume isn't up anywhere near that. Most of the growth is price. DRAM pricing went vertical and Micron sold into it. That's the whole bull case and the whole bear case in one sentence, depending on how long prices hold. 📊 http://earningsradar.org
@AIStockWire_#Micron ($MU) beats earnings estimates, reveals a $150 billion contract backlog, and forecasts another record quarter
@CNBCFastMoneyDan Nathan @RiskReversal @GuyAdami @timseymour and @grassosteve react to Micron's earnings beat $MU https://cnb.cx/3TVIrpQ
@businessMicron gave a sales forecast for the current quarter that exceeded estimates after the AI build-out fueled unprecedented demand. https://www.bloomberg.com/news/articles/2026-09-30/micron-forecast-tops-estimates-after-demand-outstrips-supply?taid=6abd8d6af6865b0001e75922&utm_campaign=trueanthem&utm_content=business&utm_medium=social&utm_source=twitter
@scottmelkerMicron $MU just posted blowout earnings as AI demand sends memory demand through the roof. Revenue hit a record $54.23 billion last quarter, up from $11.32 billion a year earlier. Net income reached $37.7 billion, compared with just $3.2 billion a year ago. And Micron expects things to get even bigger. The company guided for roughly $61.5 billion in revenue next quarter, well above Wall Street estimates of about $57 billion. Micron says customer financial commitments under long-term supply agreements have climbed to $32 billion, up from $22 billion in June. Its contracted future revenue has now grown to roughly $150 billion, up from around $100 billion last quarter. Micron has also nearly secured orders for all of its planned 2027 high-bandwidth memory supply. Why? AI. High-bandwidth memory is a critical component inside AI accelerators and data centers, and Micron is a major supplier to Nvidia $NVDA. CEO Sanjay Mehrotra says the company expects fiscal 2027 to be even stronger and is increasing investment in manufacturing to meet demand. The AI infrastructure boom is no longer just about GPUs. Memory is becoming one of the biggest bottlenecks in the entire AI buildout.
@StonkValue$MU earnings are another strong signal that AI infrastructure growth is not slowing down anytime soon. Micron expects fiscal 2027 to be another record year, with sequential revenue growth every quarter. Q4 FY26: Revenue - $54.23B vs. $51.07B expected Adj. EPS - $33.42 vs. $31.61 expected Gross Margin - 87.0% Q1 FY27 Guide: Revenue - $61.5B ± $1.5B vs. $57.02B expected Adj. EPS - $38.15 ± $1.00 vs. $35.40 expected Memory is becoming one of the biggest bottlenecks of the AI buildout and $MU is sitting right in the middle of it. Bullish $SNDK, $DRAM
@cmsinvestsCan someone please explain why AI stocks are PUMPING right now!? Did Micron actually save the stock market…
  • HomeTechnologyGamingEntertainmentWorld & BusinessScienceSportsAI
    • Home
    • Technology
    • Gaming
    • Entertainment
    • World & Business
    • Science
    • Sports
    • AI

    9 Sources

    @FinanceLancelotBREAKING: Micron $MU beats earnings estimates but reports a declining gross margin guidance of 86% 🚨 Memory stocks have always begun their cyclical decline when gross margins peak.
    @mwmarketwire🚨 MU’S BLOWOUT EARNINGS MAY ACTUALLY BE A WARNING FOR THE AI BOOM Everyone is celebrating Micron’s massive numbers. And yes ,for $MU, they are incredible. But I see something else. 🟦 MEMORY IS BECOMING MORE EXPENSIVE AI demand for HBM and memory remains enormous. Scarcity = pricing power. Great for Micron. But remember: Micron’s higher revenue is somebody else’s higher cost. And that somebody is increasingly the AI industry. 🟦 LOOK AT WHAT AI ALREADY REQUIRES GPUs. HBM / memory. Data centers. Electricity. Cooling. Networking. And increasingly: DEBT. Now add higher memory prices and expensive financing. The infrastructure bill keeps getting bigger. 🟦 BUT WHERE IS THE RETURN? This is the part almost nobody wants to discuss while AI stocks keep making new highs. OpenAI, Anthropic and xAI are growing revenues rapidly. But they are also burning enormous amounts of capital building and operating AI. And at the same time, competition is pushing the price of AI lower. DeepSeek. Chinese models. Open-source models. More competition every month. So think about this: The inputs are scarce and expensive. While… The output is becoming cheaper. 🟦 THIS IS THE AI PARADOX AI can become one of the most important technologies in history… and the investment boom behind it can STILL become financially unsustainable. Because technological success does not automatically equal: PROFIT. $MU gets paid. $NVDA gets paid. Data centers get paid. Energy companies get paid. Creditors get paid. But who ultimately captures enough profit to justify the TRILLIONS being invested into AI? That is the question I believe the market is massively underestimating. 🟦 MU’S NUMBERS DIDN’T MAKE ME MORE BULLISH ON THE AI BOOM. They made me question its economics even more. AI demand is real. The technology is real. The spending is real. But where is the return? #MWMarketWire
    @_EarningsRadar$MU revenue is up 79% Y/Y — but bit volume isn't up anywhere near that. Most of the growth is price. DRAM pricing went vertical and Micron sold into it. That's the whole bull case and the whole bear case in one sentence, depending on how long prices hold. 📊 http://earningsradar.org
    @AIStockWire_#Micron ($MU) beats earnings estimates, reveals a $150 billion contract backlog, and forecasts another record quarter
    @CNBCFastMoneyDan Nathan @RiskReversal @GuyAdami @timseymour and @grassosteve react to Micron's earnings beat $MU https://cnb.cx/3TVIrpQ
    @businessMicron gave a sales forecast for the current quarter that exceeded estimates after the AI build-out fueled unprecedented demand. https://www.bloomberg.com/news/articles/2026-09-30/micron-forecast-tops-estimates-after-demand-outstrips-supply?taid=6abd8d6af6865b0001e75922&utm_campaign=trueanthem&utm_content=business&utm_medium=social&utm_source=twitter
    @scottmelkerMicron $MU just posted blowout earnings as AI demand sends memory demand through the roof. Revenue hit a record $54.23 billion last quarter, up from $11.32 billion a year earlier. Net income reached $37.7 billion, compared with just $3.2 billion a year ago. And Micron expects things to get even bigger. The company guided for roughly $61.5 billion in revenue next quarter, well above Wall Street estimates of about $57 billion. Micron says customer financial commitments under long-term supply agreements have climbed to $32 billion, up from $22 billion in June. Its contracted future revenue has now grown to roughly $150 billion, up from around $100 billion last quarter. Micron has also nearly secured orders for all of its planned 2027 high-bandwidth memory supply. Why? AI. High-bandwidth memory is a critical component inside AI accelerators and data centers, and Micron is a major supplier to Nvidia $NVDA. CEO Sanjay Mehrotra says the company expects fiscal 2027 to be even stronger and is increasing investment in manufacturing to meet demand. The AI infrastructure boom is no longer just about GPUs. Memory is becoming one of the biggest bottlenecks in the entire AI buildout.
    @StonkValue$MU earnings are another strong signal that AI infrastructure growth is not slowing down anytime soon. Micron expects fiscal 2027 to be another record year, with sequential revenue growth every quarter. Q4 FY26: Revenue - $54.23B vs. $51.07B expected Adj. EPS - $33.42 vs. $31.61 expected Gross Margin - 87.0% Q1 FY27 Guide: Revenue - $61.5B ± $1.5B vs. $57.02B expected Adj. EPS - $38.15 ± $1.00 vs. $35.40 expected Memory is becoming one of the biggest bottlenecks of the AI buildout and $MU is sitting right in the middle of it. Bullish $SNDK, $DRAM
    @cmsinvestsCan someone please explain why AI stocks are PUMPING right now!? Did Micron actually save the stock market…
    Today's Rank

    #9

    Today's Rank

    #9