• Home
  • Technology
  • Gaming
  • Entertainment
  • World & Business
  • Science
  • Sports
  • AI
HomeTechnologyGamingEntertainmentWorld & BusinessScienceSportsAI
World & Business
Report

US September CPI: Headline Expected Near 3.6% YoY Amid Energy Pressures

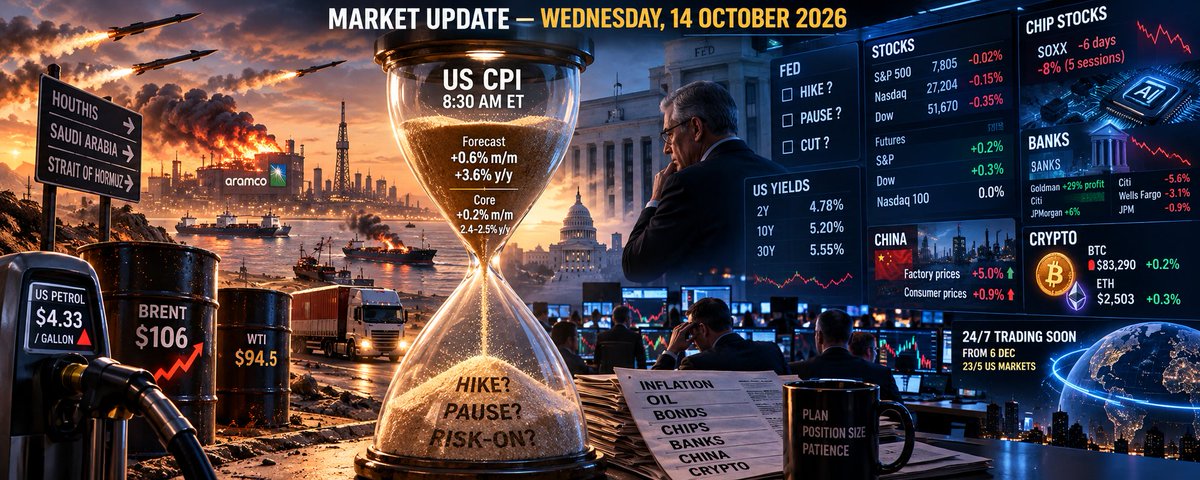
A market update projects 0.6% monthly inflation and 2.4–2.5% annual core inflation before the October 28 Fed meeting.

Mansa TeslaMT
DeFAI ScopeDS
Low Frequency⚡️LF
4 Sources, 2h ago, first seen 2h ago

TLDR

Ahead of the October 14 release, a market update forecasts US September inflation at 0.6% for the month and 3.6% year over year, up from 3.4%. It expects core inflation at 0.2% monthly and 2.4–2.5% annually. The update says markets price roughly a one-in-five chance of a Fed hike on October 28 and argues that a higher core reading could raise those odds.

Combined views

363

4 Sources, first seen 2h ago

1 saves

Combined views

363

4 Sources, first seen 2h ago

1 saves
Image: @MansaTesla on X

Sentiment

Positive——Negative

Summary

Not enough discussion yet.

No sentiment analysis available yet.

Featured Source

Sentiment

Positive——Negative

Summary

Not enough discussion yet.

No sentiment analysis available yet.

4 Sources

Mansa Tesla@MansaTeslaMARKET UPDATE — WEDNESDAY, 14 OCTOBER 2026 One number decides today's mood. US inflation lands at 8:30am New York time — with Brent crude near $106, Houthi missiles reaching Aramco's headquarters, and a Fed that still hasn't ruled out one more rate hike. On the surface, markets look calm. Underneath, chip stocks are cracking, bank shares are falling despite bumper profits, and traders are paying almost nothing for protection. 🟢 THE BIG TEST: SEPTEMBER INFLATION (8:30 ET) 🔸 Forecast: prices up 0.6% in the month and 3.6% over the year (from 3.4%). "Core" inflation is expected at +0.2% for the month and 2.4–2.5% for the year. 🔸 The driver is fuel. US petrol averaged about $4.33 a gallon in September, a record for the month (AAA data, via one secondary source). 🔸 Positioning: 22V Research says 44% of its clients expect a "risk-on" (buying) reaction. Markets price roughly a one-in-five chance of a Fed hike on 28 October. 💡 Simple Explanation: Headline inflation is what you feel at the petrol pump and supermarket. Core inflation strips out food and energy, and it's what the Fed watches to judge whether price rises are spreading into everything else. Hot headline + calm core = an energy shock, not (yet) a broad inflation problem. Why it matters: a core reading of 0.3% or more would turn an energy story into an inflation story — and put a hike firmly back on the table. 🟢 WHY PRICES ARE HOT: THE YEMEN WAR REACHES SAUDI OIL 🔸 A suspected Houthi strike caused a limited fire at an Aramco administrative building in Dhahran. No injuries; it's unclear whether it was a direct hit or debris from an interception. Missiles aimed at Riyadh and the Eastern Province were shot down. Saturday's strike on Riyadh's airport killed 13. 🔸 The Saudi-led coalition hit Houthi fuel depots near Sana'a; the Houthis have declared Saudi oil sites legitimate targets. 🔸 Escalation risk: an arms-research group reports the Houthis are importing Chinese-made parts to build a version of Iran's Kheibar Shekan missile, with a range (about 1,200 miles) covering all of Saudi Arabia and Israel. Saudi interceptor stocks are reportedly low after months of Iranian barrages. 🔸 Strait of Hormuz: two more ships struck. The one hopeful thread — Iran and Oman say they are close to a temporary safe-passage route for commercial shipping. 🔸 Trump accuses the Houthis of pushing oil higher before the 3 November midterms. 🔸 Brent: ~$106. US crude (WTI): ~$94.5. 🟢 DIESEL: THE QUIET INFLATION ENGINE 🔸 The International Energy Agency says diesel stays tight into 2027. Wholesale prices topped $200 a barrel in Singapore and hit records around $220 in Europe and the US. 🔸 Supply should turn surplus in early 2027, but not enough to refill this year's hole. Without Middle East supply returning, the IEA warns demand may have to be crushed — with heavy economic cost. 🔸 A Trump–Putin deal to release Russian diesel steadied prices on Tuesday, though the FT's Martin Wolf argues it's too small to matter. 💡 Simple Explanation: Diesel moves lorries, ships, tractors and trains. When it's expensive, almost everything you buy quietly gets dearer. 🟢 BONDS & THE FED: ARE YIELDS DOING THE FED'S JOB? 🔸 10-year US yield: 5.20% (near a two-week low). 30-year: 5.55%. 2-year: 4.78%. 🔸 Fed Governor Waller argues these high yields are already slowing the economy, reducing the need to hike. 🔸 New York Fed chief Williams still says one more hike "may be appropriate" this year, but sees no need in 2027. He also warns AI chip shortages could last beyond two years, keeping some prices high. 🔸 Jobs are cooling, not cracking: ADP's weekly average shows about 24,750 private jobs a week. Housing beat (existing home sales 3.99m vs 3.95m expected); small-business confidence dipped (NFIB 97.9). 🔸 The debt backdrop: the IMF says US debt now tops $40 trillion and growth alone can't fix it. That's a key reason long-term yields refuse to fall far. 💡 Simple Explanation: A bond yield is the interest the US government pays to borrow. At 5.2%, mortgages, car loans and company borrowing all get dearer — which slows the economy much like a Fed hike would. 🟢 STOCKS: CALM INDEX, NERVOUS INSIDES 🔸 Tuesday close: S&P 500 7,805 (−0.02%), Nasdaq 27,204 (−0.15%), Dow 51,670 (−0.35%). 🔸 This morning: S&P futures +0.2%, Dow +0.3%, Nasdaq 100 flat. Europe's STOXX 50 +0.4%. Dollar flat (DXY 102.2). 🔸 Narrow market: the S&P is up 14% this year, yet the typical stock is up less than 5% and over 200 members are down. The Nasdaq logged 408 new lows against 47 new highs. 🔸 The bull case: analysts expect third-quarter profits up about 30%, leaving the S&P at under 19 times expected earnings — its cheapest since 2023. 🔸 The warning: Goldman Sachs says options are pricing unusually small daily moves — complacency before earnings, the midterms and the Fed. 💡 Simple Explanation: The VIX "fear gauge" at 15 means traders expect calm. Goldman's point: when insurance is this cheap, a surprise hurts more. 🟢 CHIPS: AI FATIGUE SETS IN 🔸 The chip ETF (SOXX) fell for a sixth straight day, its longest losing run since May 2025. The PHLX chip index is down 8% in five sessions, though still up 70% this year. 22 of its 30 stocks sit 20%+ below their records. 🔸 Triggers: Broadcom's CEO compared some AI investment to "casino gambling"; Chinese memory maker CXMT is closing the gap; Applied Materials sank 6.7% after its investor event; SK Hynix has lost 19.5% in seven sessions. 🔸 The deeper worry: AI spending is outrunning the cash it generates, so companies are borrowing to buy chips. Mizuho sees investors growing less willing to fund that at any price. 🔸 Today's catalyst: Anthropic's reported investor day. Jefferies says many investors want to see roughly $80bn in annual recurring revenue — proof that AI spending is paying off. ASML is also in the spotlight. 🔸 Asia bounced overnight: Samsung +2.4%, TSMC +1.4%, SoftBank +3.4%. Apple hit a record $348.15 intraday, worth nearly $5 trillion. 🟢 BANKS: STRONG PROFITS, FALLING SHARES 🔸 Profits: Goldman +29%, Citi +17%, JPMorgan +6% (a rare miss). Share trading boomed — Goldman's equities revenue +72% to $6.4bn — while bond trading slipped almost everywhere. 🔸 Shares still fell: Citi −5.6%, Wells Fargo −3.1% (lending income missed), JPMorgan −0.9%. 🔸 The consumer is fine — for now. Card defaults are steady at JPMorgan and Wells Fargo. JPMorgan's CFO warned that if the Fed keeps hiking, higher unemployment and weaker loans would follow. 🔸 The FT notes bank valuations imply profits never grow again — partly on fears AI agents will shift customers' deposits to wherever pays most. 🔸 Today: Bank of America (just fined over $1.2bn by the US Treasury for money-laundering and sanctions failures), Morgan Stanley, BlackRock, State Street. 🟢 CHINA: FACTORIES HOT, SHOPPERS COLD 🔸 Factory-gate prices +5.0% on the year — fastest since June 2022 (forecast 4.5%), driven by oil and metals. 🔸 Consumer prices +0.9% (forecast 1.0%); core flat at 1.0%. 🔸 Exports reportedly jumped 36% in September, taking the nine-month trade surplus to $938bn. 💡 Simple Explanation: China makes much of the world's goods. When its factory costs rise, the rest of the world can end up "importing" that inflation. 🟢 CRYPTO: WAITING ON THE SAME NUMBER 🔸 Bitcoin $83,290 (+0.2%), Ether $2,503 (+0.3%) — parked until CPI. 🔸 Bitcoin miners pivoting to AI face the same chip shortage Williams describes, plus pickier lenders. 🔸 Midterm risk: polls lean towards Democrats winning the House, which could bring subpoenas into crypto firms, prediction markets and the Trump family's crypto links. 🟢 ONE STRUCTURAL SHIFT: WALL STREET GOES (ALMOST) 24-HOUR 🔸 From 6 December, five US exchanges including Nasdaq plan "23/5" trading — Sunday 9pm to Friday 8pm ET. Overnight volume is still tiny (about 0.1% of the day's), so expect thin trading and bigger price jumps on night-time news. 🟢 WHAT IT MEANS 🔸 Base case: hot headline, calm core. Yields ease, chips bounce, and the Fed leans towards pausing. 🔸 Risk case: core at 0.3%+. Hike odds jump from about 20%, yields head back towards highs — and with the VIX at 15, the move could be sharp. 🔸 The counterargument: even a soft print doesn't fix diesel or the Gulf. Energy shocks often seep into core prices months later. 🔸 Watch three things after 8:30: the core number, Anthropic's revenue figure for the AI trade, and any confirmation of the Hormuz safe-passage route for oil. 🗓️ CALENDAR Today (ET): 🔸 8:30am — US CPI (September) 🔸 Bank earnings: Bank of America, Morgan Stanley, BlackRock, State Street 🔸 2:00pm — Fed Beige Book 🔸 Fed speakers: Bowman, Barkin 🔸 Anthropic investor day (reportedly scheduled) This week: 🔸 Thu 8:30am — PPI (forecast +0.5%), retail sales (forecast +0.3%, prior +1.2%) 🔸 Thu 11:30pm — Fed Chair Warsh speaks 🔸 27–28 Oct — Fed meeting 🔸 3 Nov — US midterms 🔸 6 Dec — 23-hour trading begins 💭 THOUGHT FOR THE DAY "When we are no longer able to change a situation, we are challenged to change ourselves." — Viktor Frankl You can't control what the inflation number says at 8:30. You can control your plan, your position size and your patience. That's where every good trade begins. Sources: Reuters, WSJ, Financial Times, MarketWatch, Barron's, The Economist, Al Jazeera, Cointelegraph, IEA, IMF, TradingView #StockMarket #Inflation #Oil 💬 How can I make these updates better? Suggestions are always welcome.2h
DeFAI Scope@defaiscopeSeptember CPI is expected to rise from 3.4% to around 3.6% to 3.7% year on year. Higher petrol prices do most of that work. This is the last inflation print before the Fed decides on 28 October. New York Fed president John Williams already says “one more rate hike is appropriate this year.” Boston Fed president Susan Collins also backs a hike before year-end. Bitfinex’s range for Bitcoin around the release is $81,300 to $84,500. A hot print turns “one more hike” from a forecast into a schedule.2h
Low Frequency⚡️@latent_deptheCPI and PPI both land this week. Where does liquidity go? Sept CPI Wed 8:30am ET, PPI Thu, last read before the Fed's Oct 29 call. Hot print: hike odds and yields up, risk assets squeezed. Soft print, the reverse. Aug was 3.4%, core 2.4%. Not advice.15m
CryptoPulse X@CryptoPulseXgl• FED/INTEREST RATES: Fed funds target remains 3.75–4.00% after the September hike. Minutes show most officials still see another hike by year-end to fight sticky inflation. Markets price a high chance of a hold at the Oct 28 meeting, with December more in play. • INFLATION/DATA: September CPI drops today (expected ~3.6% YoY vs 3.4% prior). Energy is the main driver; core remains contained near 2.4–2.5%. Hot print could reinforce higher-for-longer rates. • DOLLAR/OIL: DXY holding 102.2 near recent highs. WTI crude $95.5–96 on supply worries, keeping inflation and rate fears elevated. • GEOPOLITICAL NEWS: Ongoing US-Iran / Strait of Hormuz tensions continue to support oil and weigh on risk appetite. Crypto remains highly sensitive to global liquidity and risk appetite. BTC holding ~$83.4k into the CPI print. #Macro #Bitcoin #Crypto14m
    • Home
    • Technology
    • Gaming
    • Entertainment
    • World & Business
    • Science
    • Sports
    • AI

    4 Sources

    Mansa Tesla@MansaTeslaMARKET UPDATE — WEDNESDAY, 14 OCTOBER 2026 One number decides today's mood. US inflation lands at 8:30am New York time — with Brent crude near $106, Houthi missiles reaching Aramco's headquarters, and a Fed that still hasn't ruled out one more rate hike. On the surface, markets look calm. Underneath, chip stocks are cracking, bank shares are falling despite bumper profits, and traders are paying almost nothing for protection. 🟢 THE BIG TEST: SEPTEMBER INFLATION (8:30 ET) 🔸 Forecast: prices up 0.6% in the month and 3.6% over the year (from 3.4%). "Core" inflation is expected at +0.2% for the month and 2.4–2.5% for the year. 🔸 The driver is fuel. US petrol averaged about $4.33 a gallon in September, a record for the month (AAA data, via one secondary source). 🔸 Positioning: 22V Research says 44% of its clients expect a "risk-on" (buying) reaction. Markets price roughly a one-in-five chance of a Fed hike on 28 October. 💡 Simple Explanation: Headline inflation is what you feel at the petrol pump and supermarket. Core inflation strips out food and energy, and it's what the Fed watches to judge whether price rises are spreading into everything else. Hot headline + calm core = an energy shock, not (yet) a broad inflation problem. Why it matters: a core reading of 0.3% or more would turn an energy story into an inflation story — and put a hike firmly back on the table. 🟢 WHY PRICES ARE HOT: THE YEMEN WAR REACHES SAUDI OIL 🔸 A suspected Houthi strike caused a limited fire at an Aramco administrative building in Dhahran. No injuries; it's unclear whether it was a direct hit or debris from an interception. Missiles aimed at Riyadh and the Eastern Province were shot down. Saturday's strike on Riyadh's airport killed 13. 🔸 The Saudi-led coalition hit Houthi fuel depots near Sana'a; the Houthis have declared Saudi oil sites legitimate targets. 🔸 Escalation risk: an arms-research group reports the Houthis are importing Chinese-made parts to build a version of Iran's Kheibar Shekan missile, with a range (about 1,200 miles) covering all of Saudi Arabia and Israel. Saudi interceptor stocks are reportedly low after months of Iranian barrages. 🔸 Strait of Hormuz: two more ships struck. The one hopeful thread — Iran and Oman say they are close to a temporary safe-passage route for commercial shipping. 🔸 Trump accuses the Houthis of pushing oil higher before the 3 November midterms. 🔸 Brent: ~$106. US crude (WTI): ~$94.5. 🟢 DIESEL: THE QUIET INFLATION ENGINE 🔸 The International Energy Agency says diesel stays tight into 2027. Wholesale prices topped $200 a barrel in Singapore and hit records around $220 in Europe and the US. 🔸 Supply should turn surplus in early 2027, but not enough to refill this year's hole. Without Middle East supply returning, the IEA warns demand may have to be crushed — with heavy economic cost. 🔸 A Trump–Putin deal to release Russian diesel steadied prices on Tuesday, though the FT's Martin Wolf argues it's too small to matter. 💡 Simple Explanation: Diesel moves lorries, ships, tractors and trains. When it's expensive, almost everything you buy quietly gets dearer. 🟢 BONDS & THE FED: ARE YIELDS DOING THE FED'S JOB? 🔸 10-year US yield: 5.20% (near a two-week low). 30-year: 5.55%. 2-year: 4.78%. 🔸 Fed Governor Waller argues these high yields are already slowing the economy, reducing the need to hike. 🔸 New York Fed chief Williams still says one more hike "may be appropriate" this year, but sees no need in 2027. He also warns AI chip shortages could last beyond two years, keeping some prices high. 🔸 Jobs are cooling, not cracking: ADP's weekly average shows about 24,750 private jobs a week. Housing beat (existing home sales 3.99m vs 3.95m expected); small-business confidence dipped (NFIB 97.9). 🔸 The debt backdrop: the IMF says US debt now tops $40 trillion and growth alone can't fix it. That's a key reason long-term yields refuse to fall far. 💡 Simple Explanation: A bond yield is the interest the US government pays to borrow. At 5.2%, mortgages, car loans and company borrowing all get dearer — which slows the economy much like a Fed hike would. 🟢 STOCKS: CALM INDEX, NERVOUS INSIDES 🔸 Tuesday close: S&P 500 7,805 (−0.02%), Nasdaq 27,204 (−0.15%), Dow 51,670 (−0.35%). 🔸 This morning: S&P futures +0.2%, Dow +0.3%, Nasdaq 100 flat. Europe's STOXX 50 +0.4%. Dollar flat (DXY 102.2). 🔸 Narrow market: the S&P is up 14% this year, yet the typical stock is up less than 5% and over 200 members are down. The Nasdaq logged 408 new lows against 47 new highs. 🔸 The bull case: analysts expect third-quarter profits up about 30%, leaving the S&P at under 19 times expected earnings — its cheapest since 2023. 🔸 The warning: Goldman Sachs says options are pricing unusually small daily moves — complacency before earnings, the midterms and the Fed. 💡 Simple Explanation: The VIX "fear gauge" at 15 means traders expect calm. Goldman's point: when insurance is this cheap, a surprise hurts more. 🟢 CHIPS: AI FATIGUE SETS IN 🔸 The chip ETF (SOXX) fell for a sixth straight day, its longest losing run since May 2025. The PHLX chip index is down 8% in five sessions, though still up 70% this year. 22 of its 30 stocks sit 20%+ below their records. 🔸 Triggers: Broadcom's CEO compared some AI investment to "casino gambling"; Chinese memory maker CXMT is closing the gap; Applied Materials sank 6.7% after its investor event; SK Hynix has lost 19.5% in seven sessions. 🔸 The deeper worry: AI spending is outrunning the cash it generates, so companies are borrowing to buy chips. Mizuho sees investors growing less willing to fund that at any price. 🔸 Today's catalyst: Anthropic's reported investor day. Jefferies says many investors want to see roughly $80bn in annual recurring revenue — proof that AI spending is paying off. ASML is also in the spotlight. 🔸 Asia bounced overnight: Samsung +2.4%, TSMC +1.4%, SoftBank +3.4%. Apple hit a record $348.15 intraday, worth nearly $5 trillion. 🟢 BANKS: STRONG PROFITS, FALLING SHARES 🔸 Profits: Goldman +29%, Citi +17%, JPMorgan +6% (a rare miss). Share trading boomed — Goldman's equities revenue +72% to $6.4bn — while bond trading slipped almost everywhere. 🔸 Shares still fell: Citi −5.6%, Wells Fargo −3.1% (lending income missed), JPMorgan −0.9%. 🔸 The consumer is fine — for now. Card defaults are steady at JPMorgan and Wells Fargo. JPMorgan's CFO warned that if the Fed keeps hiking, higher unemployment and weaker loans would follow. 🔸 The FT notes bank valuations imply profits never grow again — partly on fears AI agents will shift customers' deposits to wherever pays most. 🔸 Today: Bank of America (just fined over $1.2bn by the US Treasury for money-laundering and sanctions failures), Morgan Stanley, BlackRock, State Street. 🟢 CHINA: FACTORIES HOT, SHOPPERS COLD 🔸 Factory-gate prices +5.0% on the year — fastest since June 2022 (forecast 4.5%), driven by oil and metals. 🔸 Consumer prices +0.9% (forecast 1.0%); core flat at 1.0%. 🔸 Exports reportedly jumped 36% in September, taking the nine-month trade surplus to $938bn. 💡 Simple Explanation: China makes much of the world's goods. When its factory costs rise, the rest of the world can end up "importing" that inflation. 🟢 CRYPTO: WAITING ON THE SAME NUMBER 🔸 Bitcoin $83,290 (+0.2%), Ether $2,503 (+0.3%) — parked until CPI. 🔸 Bitcoin miners pivoting to AI face the same chip shortage Williams describes, plus pickier lenders. 🔸 Midterm risk: polls lean towards Democrats winning the House, which could bring subpoenas into crypto firms, prediction markets and the Trump family's crypto links. 🟢 ONE STRUCTURAL SHIFT: WALL STREET GOES (ALMOST) 24-HOUR 🔸 From 6 December, five US exchanges including Nasdaq plan "23/5" trading — Sunday 9pm to Friday 8pm ET. Overnight volume is still tiny (about 0.1% of the day's), so expect thin trading and bigger price jumps on night-time news. 🟢 WHAT IT MEANS 🔸 Base case: hot headline, calm core. Yields ease, chips bounce, and the Fed leans towards pausing. 🔸 Risk case: core at 0.3%+. Hike odds jump from about 20%, yields head back towards highs — and with the VIX at 15, the move could be sharp. 🔸 The counterargument: even a soft print doesn't fix diesel or the Gulf. Energy shocks often seep into core prices months later. 🔸 Watch three things after 8:30: the core number, Anthropic's revenue figure for the AI trade, and any confirmation of the Hormuz safe-passage route for oil. 🗓️ CALENDAR Today (ET): 🔸 8:30am — US CPI (September) 🔸 Bank earnings: Bank of America, Morgan Stanley, BlackRock, State Street 🔸 2:00pm — Fed Beige Book 🔸 Fed speakers: Bowman, Barkin 🔸 Anthropic investor day (reportedly scheduled) This week: 🔸 Thu 8:30am — PPI (forecast +0.5%), retail sales (forecast +0.3%, prior +1.2%) 🔸 Thu 11:30pm — Fed Chair Warsh speaks 🔸 27–28 Oct — Fed meeting 🔸 3 Nov — US midterms 🔸 6 Dec — 23-hour trading begins 💭 THOUGHT FOR THE DAY "When we are no longer able to change a situation, we are challenged to change ourselves." — Viktor Frankl You can't control what the inflation number says at 8:30. You can control your plan, your position size and your patience. That's where every good trade begins. Sources: Reuters, WSJ, Financial Times, MarketWatch, Barron's, The Economist, Al Jazeera, Cointelegraph, IEA, IMF, TradingView #StockMarket #Inflation #Oil 💬 How can I make these updates better? Suggestions are always welcome.2h
    DeFAI Scope@defaiscopeSeptember CPI is expected to rise from 3.4% to around 3.6% to 3.7% year on year. Higher petrol prices do most of that work. This is the last inflation print before the Fed decides on 28 October. New York Fed president John Williams already says “one more rate hike is appropriate this year.” Boston Fed president Susan Collins also backs a hike before year-end. Bitfinex’s range for Bitcoin around the release is $81,300 to $84,500. A hot print turns “one more hike” from a forecast into a schedule.2h
    Low Frequency⚡️@latent_deptheCPI and PPI both land this week. Where does liquidity go? Sept CPI Wed 8:30am ET, PPI Thu, last read before the Fed's Oct 29 call. Hot print: hike odds and yields up, risk assets squeezed. Soft print, the reverse. Aug was 3.4%, core 2.4%. Not advice.15m
    CryptoPulse X@CryptoPulseXgl• FED/INTEREST RATES: Fed funds target remains 3.75–4.00% after the September hike. Minutes show most officials still see another hike by year-end to fight sticky inflation. Markets price a high chance of a hold at the Oct 28 meeting, with December more in play. • INFLATION/DATA: September CPI drops today (expected ~3.6% YoY vs 3.4% prior). Energy is the main driver; core remains contained near 2.4–2.5%. Hot print could reinforce higher-for-longer rates. • DOLLAR/OIL: DXY holding 102.2 near recent highs. WTI crude $95.5–96 on supply worries, keeping inflation and rate fears elevated. • GEOPOLITICAL NEWS: Ongoing US-Iran / Strait of Hormuz tensions continue to support oil and weigh on risk appetite. Crypto remains highly sensitive to global liquidity and risk appetite. BTC holding ~$83.4k into the CPI print. #Macro #Bitcoin #Crypto14m
    Today's Rank

    —

    Not ranked yet

    Today's Rank

    —

    Not ranked yet