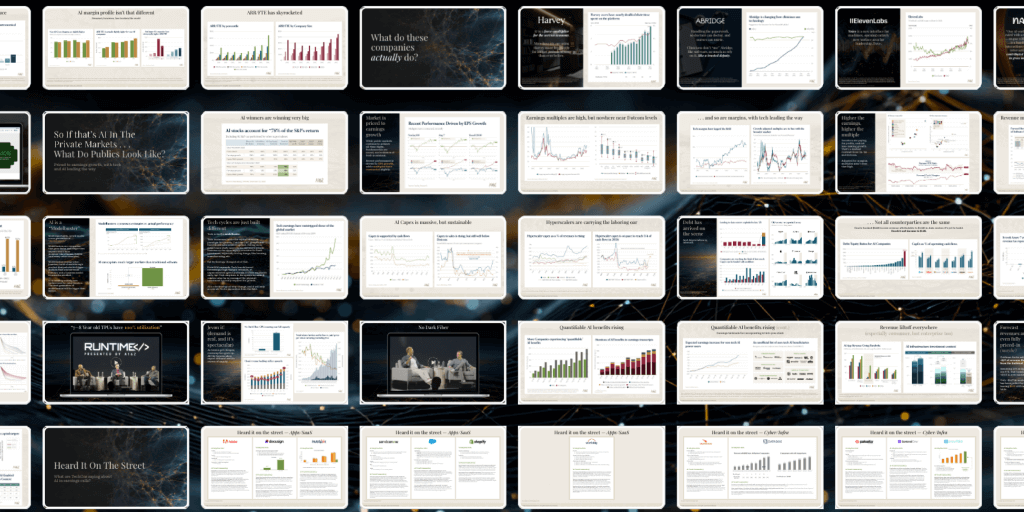
Andreessen Horowitz has released “State of Markets II,” its second State of Markets report, billed as “100+ Charts On The State of Markets (1H’26).” Published Sept. 30 and authored by David George, the report tries to explain how the AI boom is changing where money is being made across tech and how far that spending has actually translated into everyday adoption.
The sharpest formulation in the report is its argument that the AI buildout has effectively redirected profits from the largest cloud and platform companies to chip suppliers. In a chart shared alongside the release, a16z writes that “Big Tech’s profits have become chipmakers’ profits,” with approximate free cash flow moving from “Hyperscalers: $275B → $0” and “Semiconductors: $50B → $400B” from 2022 to today.
That shift is part of a broader case George makes in the written overview: that tech markets are rotating “from bits to atoms.” In his framing, software dominated the last cycle, while this one is being driven by hardware and physical infrastructure. The firm says the AI buildout has created a surge in demand not just for semiconductors, but also for power and networking, and that this demand has been financed largely by historically large hyperscaler profits and, increasingly, by debt.
a16z extends that argument beyond AI chips alone. The report says both public and private capital are now pouring into compute, memory, power, robotics, manufacturing and defense, describing the current moment as a revival for more capital-intensive parts of the technology economy after years in software’s shadow.
But the report pairs that supply-side boom with a much more cautious view of adoption. George writes that AI adoption is “broad” but “relatively shallow.” Nearly 30% of S&P 500 companies, he says, report some “quantifiable impact” from AI, yet only about 2% report any tracked metric. In a companion post, George similarly argued that diffusion into companies is still very early, adding that median AI vendor spending among the top 1% of companies is eight times that of the top 10%.
The same pattern appears on the consumer side in the report’s telling. a16z says paid consumer AI penetration is still tiny, writing that as of April, only about 2% of US households were paying for some AI service, even if that figure has since risen.
Taken together, the message is that AI infrastructure spending has arrived faster than mature usage. The report argues that demand for compute is still outpacing supply even though measurable enterprise deployment and paid household adoption remain limited by comparison.
That tension helps explain why the report casts the current moment as bigger than a normal software cycle. Rather than presenting AI as just another application wave, a16z argues it is helping pull investment toward physical systems and industrial capacity, from chips and memory to the electric grid, robotics, manufacturing and defense.
The report does not frame that as a short-lived detour away from software so much as a wider expansion of what counts as the tech economy. In George’s summary, “tech is the everything cycle,” and AI’s next phase depends not only on better models and apps, but on how quickly companies connect them to real data, workflows and infrastructure.